Kenya has spent the last two decades quietly rewriting the global rulebook on money movement. Long before “fintech” became a buzzword in Silicon Valley boardrooms, Kenyans were already sending cash across town with a text message.
M-Pesa turned a feature phone into a bank branch, and in doing so, it taught an entire generation that money should move as easily as a conversation. That lesson has not been forgotten. If anything, it has hardened into an expectation. And that expectation is now the single biggest force shaping where Kenyan banking goes next.
Walk into any matatu stage, market, or shopping mall in Nairobi and you will see the same behaviour repeated a thousand times a day: a phone tapped, a code entered, a transaction confirmed in seconds. What has changed is not the habit itself but the tolerance for its cost. A generation raised on near-instant, near-free mobile money no longer accepts the old banking logic of charges for every touchpoint, a fee to withdraw your own salary, a fee to move money between banks, a fee to check a balance. That model was built for a slower, more captive customer base. It is not built for Kenya in 2026.
This is why the next chapter of Kenyan finance will be won not by whoever has the flashiest app, but by whoever removes the most friction and cost from everyday transactions. The banks that thrive will be the ones that understand a simple truth: in a market this mobile-first, this price-sensitive, and this comfortable with digital rails, low-cost, or no-cost, banking is not a marketing gimmick. It is the product.
Three forces are driving this shift. First, interoperability has matured. PesaLink, the instant bank-to-bank transfer system built by Kenyan banks themselves, has made moving money between institutions as easy as mobile money once made moving money between phones. Second, a genuinely digital-native customer base has grown up. Young professionals, small business owners, and gig workers now manage most of their financial lives from a screen, and they compare banking apps the way they compare ride-hailing apps, on speed, reliability, and cost, full stop. Third, competition has intensified to the point where fees themselves have become a competitive weapon rather than a quiet revenue line. Banks that cling to legacy charge structures are discovering, often painfully, that customers vote with their thumbs and simply move their money elsewhere.
The winners in this environment will share a few traits. They will treat digital channels as the primary relationship, not an add-on to a branch network. They will price transactions the way mobile money once did, assuming volume and loyalty will follow, rather than trying to extract margin from every single tap. And they will build products around the realities of Kenyan financial life: remittances from family working abroad, small merchants who need to move float quickly, and everyday people who simply want their salary to reach them, and their bills to be paid, without a toll booth at every step.
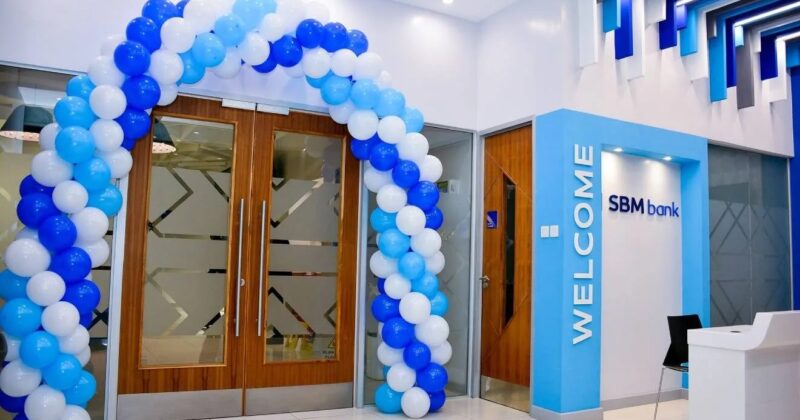
This is exactly the space SBM Bank Kenya has chosen to compete in, and it is worth paying attention to. Rather than treating digital payments as a side feature, SBM has stripped out the fees that have quietly drained Kenyan bank accounts for years. Customers enjoy free interbank transfers for amounts below Kes 1 Million via Pesalink on Mfukoni , meaning money can move between banks without the usual charge eating into it. ATM withdrawals are free too, and notably this extends beyond Kenya’s borders; customers can withdraw from any Mastercard-branded ATM globally without incurring a fee, a welcome offer in a market where international withdrawal charges are often steep and opaque.
Add to that free PesaLink transfers and free M-Pesa deposits, and what emerges is a banking relationship built around the same principle that made mobile money a national habit in the first place: money should move freely, without a tax on every transaction. For a market that has already shown it will abandon costly systems in favor of cheap, fast ones, this positioning is not just customer-friendly, it is strategically shrewd. It signals an understanding that in Kenya’s payments future, the banks that win will not be the ones that charge the most for convenience, but the ones that make convenience itself the free, standard baseline. SBM Bank Kenya’s approach offers an early glimpse of what that future looks like in practice.